Coronavirus crisis and free trade
Or about why, in times of crisis, free trade is not questioned

Luciana Ghiotto [1]
The depth of the crisis we are experiencing is undeniable. Numerous diagnoses point to a crisis of capitalism, a financial crisis, an ecological and climate crisis, a health crisis, a crisis of global institutions, among other ways of understanding it. Undoubtedly, one of the most dramatic forms this crisis has taken is its financial manifestation. In January 2020, with the surge in coronavirus cases in China, bondholders engaged in a massive sell-off, triggering alarm in global financial markets, culminating in the shockwaves of early March. The expansion of debt in recent years has been exponential. Since 2017, there has been renewed growth in public debt issuance in the most advanced economies, surpassing post-World War II levels of public debt [2] . Faced with this new earthquake in the financial system, states are once again emerging, as they did in 2008, as a lifeline for bankrupt companies and a support for the fragile global financial system. Faced with crises, economic establishments not only do not question the interventionist role of the State, but they demand it.
However, this crisis we are just beginning to navigate is revealing a much deeper problem: capitalism's inability to restructure production in a way that guarantees a long-term increase in the rate of profit. This manifests as a crisis of overproduction in a context where the economy and trade have not expanded significantly since 2008. Over the last decade, the global economy has been characterized by slow and weak growth. Nevertheless, during the same period, we have seen an expansion of the network of trade and investment agreements that attempt to create frameworks of certainty for investors on a global scale. The legal architecture, comprised of thousands of treaties, has been evolving in accordance with the way global value chains develop, as well as with certain necessary forms of state regulation in the face of the chaos of accumulation. The integration of production networks has reached such a level that free trade cannot be questioned, nor are states permitted to adopt practices that tend to erect protectionist barriers.
In this essay, we will explain that, in crisis contexts, the role of states as lenders of last resort, regulators of economies, and saviors of productive enterprises on the verge of bankruptcy becomes acceptable (and necessary). However, they cannot erect extraordinary barriers to the circulation of capital and goods. Given the profound interconnectedness of global production networks, some state regulation is acceptable, but not a complete halt to trade liberalization; the wheel must keep turning.
The 2008 crisis, the start of the great recession and the “new generation” Free Trade Agreements
To understand the current situation, it is essential to look back at the 2007-2008 crisis. This crisis can be understood as the beginning of a major recession that has not been resolved and has not led to a new, sustained process of capital accumulation [3] ; in fact, the following ten years can be seen as the intermittent expression of that crisis [4] . The 2008 crisis did not end because states played a crucial role in bailing out productive companies and the bankrupt financial sector, thus preventing a successful capital restructuring that would have allowed for a short-term exit from the crisis cycle. In this way, the crisis was pushed forward through the exponential growth of debt.
After 2008, the global economy was characterized by anemic or weak growth in the major economies. This growth was marked by an overaccumulation of productive capital [5] . Despite low interest rates and a flood of liquidity during the first decade of the new century, sustained economic growth was not generated. During the 2008 crisis, global exports slowed by 3,4%, and in 2009 they decreased by 11,3% [6] , an unprecedented collapse since the 1930s crisis. Growth and trade levels stabilized in the post-crisis period thanks to the role of the Chinese economy as a major consumer of natural resources and a mobilizer of global investment through infrastructure projects such as the Belt and Road Initiative . However, since mid-2018, there has been a renewed decline in global industrial activity and trade. In the last quarter of 2019, trade fell by 1,2% [7] . Before the start of the pandemic, the OECD's global economic growth forecast was 2,9% for 2020, although the International Monetary Fund (IMF) recently announced a contraction of nearly 3% in the global economy, a decline worse than that experienced after the 2008 crisis [8] . The short-term problem for emerging from this crisis is that China is not in a position to play the same role as in the post-2008 crisis, because China itself has become the scene of global overaccumulation, and because it has been the country directly affected by COVID-19, generating a widespread slowdown in production [9].
In 2008, the major powers attempted a coordinated exit strategy by relaunching a new, updated G-20 to address the global crisis. The convening of an expanded forum (formerly the G7) demonstrated the need to seek a degree of cooperation to overcome the crisis, beyond the central (financial and political) role of the United States. The general agreement was that a new global order would be established, based on global supervision, order, and regulation [10] . Most importantly, the G-20, in its 2008 and 2009 meetings, agreed to allow the necessary fiscal measures to stabilize the global financial system. However, it also agreed not to succumb to protectionist temptations, given that global production networks would require free and open trade to function [11] . It was a matter of increasing regulation in a context of continued liberalization. The declaration of the G20 Summit in November 2008 in Washington stressed the importance of not isolating oneself, rejecting protectionism and “not setting up barriers to investment or trade in goods and services, imposing new restrictions on imports, or putting in place measures (…) to stimulate exports” [12].
The G20's "regulatory" approach failed; in fact, it was quickly abandoned. However, the need to advance certain acceptable modes of state intervention in crisis situations was reflected in the free trade agreements (FTAs) negotiated after 2008, especially the so-called mega-regional agreements. The connection between the 2008 crisis and the latest wave of FTAs is particularly evident in the incorporation of new issues relevant to capital accumulation within the framework of the internationalization of production, especially e-commerce and digital services. But the key to understanding the connection with the crisis lies in the fact that these agreements incorporate a certain reconfiguration of the regulatory functions of states, especially with regard to the financial sector [13] . The Trans-Pacific Partnership (TPP), negotiated by the US (although the US later withdrew), added a chapter on Financial Services that accepts a greater bailout role for states, based on the incorporation of exceptions to the National Treatment clause for the foreign financial sector. Thus, the role of the state in bailing out “national” banks and the financial sector in crisis situations is permitted. As we can see, the new wave of treaties of the last decade can be interpreted in light of the (temporary) solution found for the 2008 crisis.
But the recovery from the 2008 crisis did not generate a boost for global GDP growth and increased trade; instead, it relied on credit expansion. The ratio of total debt (households, businesses, and governments) to global GDP stands at 322%, a figure that rises to 383% in developed countries [14] . Credit became a kind of buffer to prevent a major crisis, which was once again postponed. Therefore, the only short-term solution for the system as a whole is to accept the central role of states as the system's "saviors" [15] . Now, as in 2008, the bailout is carried out by states and their central banks, creating the necessary monetary stimulus to keep the machinery of the financial system (banks, insurers, hedge funds) and the productive system running smoothly (recall that in 2008 the US government also bailed out mega-corporations like General Motors). Once again, the crisis-and-restructuring was prolonged and postponed [16].
The problem is that this push forward partially imploded between December 2019 and March 2020 with the production shutdown in China, which severely impacted industries like the automotive sector. It's worth noting that 9% of China's car production takes place in Wuhan, the epicenter of the pandemic. This shutdown created enormous uncertainty about the future of the entire production system, due to the inability to predict how long the value chains, with China as their main link, would remain paralyzed. The shutdown quickly manifested as a massive sell-off of stocks and a crisis in the financial system. In March, the markets collapsed, but with the intervention of the US Federal Reserve ( Fed) and the European Central Bank, global markets were stabilized, preventing the dollar from skyrocketing. However, this intervention was much stronger than any role these institutions have played since the 2008 crisis. Therefore, according to Adam Tooze, we are only at the beginning of the shockwave of a crisis that could explode in a short time [17].
Trade is not to be touched: the need for the circulation of goods in times of crisis
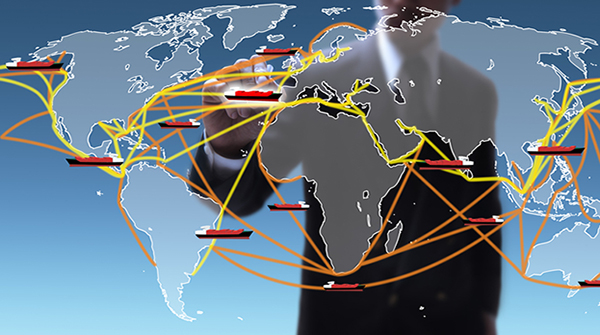
The spread of the coronavirus in China and the subsequent factory closures had a significant impact on all markets, especially due to their high dependence on production chains linked to that country. By the beginning of 2020, a widespread slowdown was already evident in three sectors [18] . First, in production (supply crisis) due to social distancing measures. This is already generating a sharp increase in idle capacity and enormous losses in various sectors of the economies. Second, this standstill leads to a drop in global demand. Without production, there is less need for coal, iron, copper, or other minerals. The drop in demand for commodities from developed countries and China is already impacting economies dependent on these exports, such as those in Latin America. Third, the slowdown in supply and demand is reflected in a brutal drop in circulation, in trade. The WTO estimates that the drop in world trade could range between 13% and 32%, depending on the speed and capacity of states to address the crisis [19] . For its part, UNCTAD projected a drop in foreign direct investment of between 30% and 40% until 2021 [20].
Faced with this grim situation, various diagnoses and proposals from governmental institutions and forums are circulating regarding the crisis in global trade. Several organizations, such as the WTO, UNCTAD, and ECLAC, and forums like the OECD and the G20, have published statements with a series of public policy proposals aimed at keeping trade open and functioning. The common position is that states need to intervene to resolve (in some way) the health crisis and guarantee bailouts for businesses. But there is also a consensus that open trade and global value chains are fundamental drivers for recovery from the economic crisis. Just as the active role of states is mitigating and containing the economic shock, in the area of trade, governments should only implement “necessary, effective, and scientifically proven measures to address the Covid-19 pandemic” [21].
The concern is that the crisis will trigger a wave of protectionist policies and increased tariffs, as has happened in other times of crisis. In this regard, Roberto Azevêdo, Director-General of the WTO, stated that “governments are introducing fiscal and monetary stimulus” to address the crisis, and “that is positive.” According to Azevêdo, trade has an important role to play in the “global response” that this crisis requires, since open trade will help bring about “the fastest and strongest economic recovery for all” [22] . The OECD maintains that it is crucial for states to boost “confidence in global trade and markets by improving transparency regarding trade-related policy measures and intentions,” as well as “avoiding making the outlook more dire by implementing unnecessary restrictions and other trade barriers” [23] . In this sense, it is necessary to improve coordination in facilitating global trade, and especially in digital trade (a sector that is actually benefiting from the crisis). And if technical barriers to trade (or non-tariff barriers) are applied, then the need for such a policy must be based on scientific evidence, as is made explicit in most of the free trade agreements signed globally.
Meanwhile, several states are negotiating or approving free trade agreements (FTAs) during the pandemic, demonstrating that free trade is not in question. Numerous examples illustrate this: Ecuador's National Assembly, in the midst of a health crisis that has made it one of the countries with the highest COVID-19 mortality rates in the region, approved an agreement with the European Free Trade Association (EFTA) countries on April 21 [24] , and in the same week concluded negotiations for an FTA with Chile. The Vietnamese Parliament is preparing to approve a trade agreement with the EU at its next meeting at the end of May, via parliamentary videoconference [25] . At the same time, the EU continues its trade negotiations with the US, China, Australia, and New Zealand during the pandemic [26] , while also announcing the end of negotiations for the "modernization" of the trade agreement with Mexico, a move denounced by numerous social organizations [27] . Mercosur announced that the next round of negotiations for a free trade agreement with South Korea will take place in May, although now without Argentina's participation (although Argentina made it clear that it is not withdrawing from the final stage of technical and legal review of the agreement with the EU) [28] . Meanwhile, within the framework of NAFTA, the US has pressured Mexico to reopen plants located on the border amid widespread work stoppages because workers are denouncing the lack of hygiene measures and health protections [29].
Free trade is untouchable. The entire system increasingly depends on the rapid, easy, and unhindered circulation of capital. “Deregulation” is not the same as “liberalization.” Regulating the banking sector, for example, is acceptable in the eyes of the World Bank [30] or the G20 in the post-2008 crisis, but the liberalization of commodity markets is not up for debate. In early April, the Financial Times predicted the end of neoliberalism and called for a new “social contract” in which states play a more active role in the economy [31] , granting large loans [32] and even the power to nationalize bankrupt companies (as the EU has recently allowed [33] ). But in this corporate bailout, it is essential to ensure that companies sell . In materialist terms, the commodity must be realized in the global market, thus completing the cycle of capital reproduction. This implies that the wheel of capital keeps turning : that goods continue to circulate, that customs are not restricted, and that unnecessary tariff (or non-tariff) barriers that hinder the import and export of products are not established. As David Harvey would say, that the cycle of “mad consumption” [34] continues, because it keeps the wheel of production running.
If “globalization,” or the process of internationalization of capital, did anything, it was to reduce or eliminate barriers to give free rein to capital. The entire world was transformed into a single market under the logic of capitalist accumulation. From the perspective of capital, free movement is indeed crucial, given the centrality of raw material extraction, access to cheap and disciplined labor, and the final location of production. But we currently find ourselves with a system characterized by overcapacity, the existence of enormous amounts of capital and surplus production with lower profit margins, coupled with a decline in global consumption. Signing new free trade agreements and maintaining existing ones do not guarantee increased exports or attract more foreign investment. Their sole purpose is to impose the best possible conditions for the free movement of capital and goods. But without an effective restructuring of capital on a global scale, the rate of profit will not recover, nor will trade be able to generate an economic recovery “that benefits everyone,” as Roberto Azevedo argues.
The (fleeting) success of capitalism thus seems to be based on a new, brutal expansion of credit, with states and their central banks as the undisputed protagonists. At the same time, states are attempting to circumvent the health and financial crisis with policies of monetary expansion, job protection, and production support. They are also trying to attract some of the circulating capital to their territories to balance their national accounts, for which they are strengthening the confidence of bankers and investors that their profits are guaranteed, for example, by negotiating new free trade agreements and maintaining existing ones. The problem is that if the crisis lasts for several months, these expansionary measures will begin to falter: for example, emerging economies like those in Latin America do not have the economic capacity of developed countries to sustain enormous subsidies for very long. Furthermore, governments will find that existing free trade agreements severely restrict their room for maneuver in implementing domestic market policies that would help them emerge from the crisis. In a context of enormous uncertainty, then, the trap set by governments is obvious.
No individual (or collective) state could resolve the crisis, only prolong it into the future, as happened in 2008. Faced with this inherent incapacity of states, the problem then falls on the side of non-capitalist solutions to the crisis: how do we build a “post-coronavirus world” that is not based on bailing out speculators but focuses on people? Can we move forward with new global social pacts [35] , with the construction of new internationalisms that place the irrationality of trade at the heart of their critique and propose radical and viable alternatives? This will ultimately depend on the formation of a favorable balance of power that allows for new global constructions.
[1] Researcher at CONICET (Argentina), School of Politics and Government (EPYG-UNSAM). Collaborator at the Transnational Institute (TNI). Member of the CLACSO Working Group “ Lex mercatoria , human rights and democracy”. The author thanks Rodrigo F. Pascual and Julio C. Gambina for their clarifying comments.
[2] François Chesnais: “The world economy at the beginning of the great Covid-19 recession”, April 2020. In: www.herramienta.com.ar/articulo.php?id=3168
[3] Rolando Astarita: “The global crisis is accelerating and deepening”, April 2020, on Blog de Rolando AstaritaDavid Harvey: “Anti-capitalist politics in times of COVID-19”, March 2020, in AA.VV., Wuhan SopaDavid Harvey: The enigma of capital and the crises of capitalism, 2012, Madrid, Akal; Chesnais, op. cit.
[4] Adam Tooze: “Shockwave”, April 2020, London Review of Books.
[5] Astarita, op.cit.
[6] Leo Panitch and Sam Gindin: The construction of global capitalism; the political economy of the American empire, 2015, Madrid, Akal.
[7] WTO in: https://www.wto.org/english/res_e/statis_e/daily_update_e/merch_latest.pdf
[8] Inforegion in: https://www.inforegion.com.ar/2020/04/14/por-el-coronavirus-la-economia-mundial-caera-un-3/
[9] Chesnais, op.cit.
[10] Jorge Arguello: Who rules the world? The role of the G-20 in the new world order, 2018, Buenos Aires, Intellectual Capital.
[11] Panitch and Gindin, op.cit.
[12] G20: “Summit on Financial Markets and the World Economy”, in: https://georgewbush-whitehouse.archives.gov/infocus/financialmarkets/index.html
[13] Luciana Ghiotto: “Free Trade Agreements and Crisis: Notes for a Critique of New Generation Treaties”, in Orozco (coord.) From NAFTA to USMCA: 25 years of free trade, Mexico City, CLACSO GT Borders, Regionalization and Globalization, 2019 (in press).
[14] Chesnais, op.cit.
[15] Julio C. Gambina: “The pandemic aggravates the recessionary trend and its regressive effects on employment and popular income,” March 21, 2020; in Julio Gambina's Blog.
[16] John Holloway: “The Corona-storm”; course The Storm, Coronacrisis IApril 2020. In: www.comunizar.com.ar
[17] Tooze, op.cit.
[18] Astarita, op.cit.
[19] WTO, in: https://www.wto.org/spanish/news_s/pres20_s/pr855_s.htmRevised in April 2020.
[20] UNCTAD, Investment Trends Monitor: Impact of the COVID-19 on global FDI and GVCsMarch 2020. In: https://unctad.org/en/PublicationsLibrary/diaeiainf2020d3
[21] Statement: The Trade Policy Response to Covid-19: A Call for Urgent OECD Action; Business at OECD, 7 April 2020.
[22] Video message from the WTO Director-General, Roberto Azevedo: Trade Forecasts 2020. In: https://www.wto.org/spanish/tratop_s/covid19_s/covid19_s.htm#dgvideoRevised in April 2020.
[23] OECD (2020) COVID-19 and international trade: issues and actionsPolicy Brief, April 10, 2020, in: https://read.oecd-ilibrary.org/view/?ref=128_128542-3ijg8kfswh&title=COVID-19-and-international-trade-issues-and-actions
[24] https://www.eltelegrafo.com.ec/noticias/economia/4/acuerdo-comercial-efta-bienes
[25] https://www.bilaterals.org/?vietnam-s-parliament-to-ratify-fta&lang=en
[26] Swedish Trade Policy, April 24, 2020, in: https://twitter.com/setradepolicy/status/1253699231371661313
[27] https://www.bilaterals.org/?preocupante-renovacion-del-acuerdo&lang=en
[28] Interview with Luciana Ghiotto: “Argentina needs to reach an agreement with the EU,” by Vanessa Dourado. April 26, 2020. In: https://americalatinasintlc.org/2020/04/26/argentina-necesita-salir-del-acuerdo-mercosur-ue/
[29] https://www.bilaterals.org/?us-pressures-mexico-to-reopen&lang=en
[30] In Panitch and Gindin, op.cit.
[31] Financial Times: “Virus lays bare the frailty of the social contract”, April 3, 2020; in: https://www.ft.com/content/7eff769a-74dd-11ea-95fe-fcd274e920ca
[32] In Argentina, the government announced in April 2020 a support package for businesses that included the disbursement of 70 billion pesos in supplementary wages, 11 billion pesos in loans for self-employed workers, and 26 billion pesos in guarantees for those loans. In total, the government announced a commitment of approximately USD 1.000 billion for SMEs. https://www.infobae.com/economia/2020/04/20/el-paquete-total-del-gobierno-para-ayudar-a-empresas-y-cuentapropistas-suma-850000-millones-3-del-pbi/
[33] https://www.cronista.com/internacionales/Europa-se-prepara-para-la-nacionalizacion-masiva-de-empresas-20200423-0002.html
[34] David Harvey, 2020, op.cit.
[35] Maristella Svampa. “Reflections for a post-coronavirus world”, Nueva Sociedad, April 2020.
[+] Thinking about the pandemic

If you would like to receive more information about CLACSO's training programs:
[widget id=”custom_html-57″]
to our email lists.